
Africa Could Recover Billions by Fixing Cross-Border Payment Rules
Africa could recover billions of dollars lost to expensive cross-border transactions if countries harmonise their digital payment regulations, according to a framework backed by the African Union Commission and AfricaNenda Foundation. The proposal estimates that implementing the framework would require about $120 million and could help unlock a cross-border payments market projected to grow from $329 billion in 2025 to nearly $1 trillion by 2035.
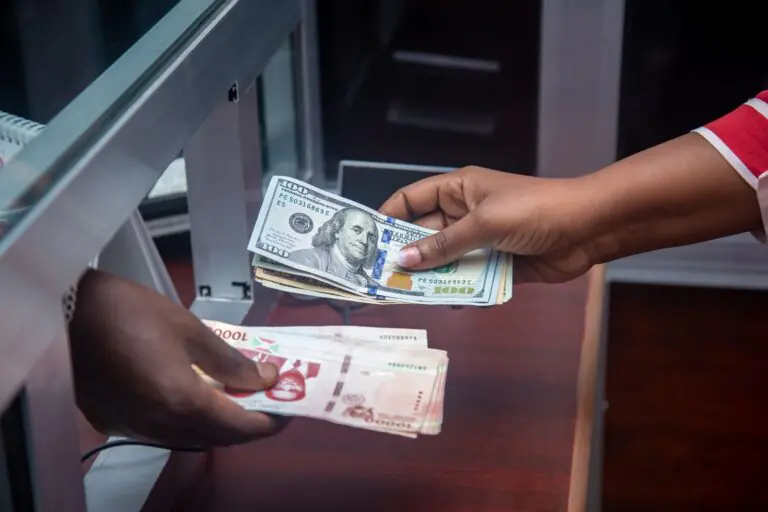
The problem, according to experts, is increasingly less about payment technology and more about incompatible national regulations. Different requirements for licensing, customer verification, anti-money laundering controls, data protection and currency settlement often make it difficult for payment providers to operate across multiple African markets. The proposed framework would seek to align these rules and allow existing national payment systems to connect more efficiently.
The financial cost of the current fragmentation is significant. Remittances to sub-Saharan Africa cost an average of 7.9 per cent, well above the global Sustainable Development Goal target of three per cent. Currency conversion through major international currencies is also estimated to cost the continent about $5 billion annually. Reducing transaction fees could potentially return up to $1 billion each year to users, while making cross-border payments cheaper could also support businesses, digital finance and intra-African trade.
The initiative proposes a 10-year implementation process, beginning with the adoption of a binding African Union legal instrument, an enforcement structure under the Association of African Central Banks and the mobilisation of the $120 million implementation fund. Later stages would focus on linking instant-payment systems, mutual recognition of customer-verification requirements and expanding participation across the continent. However, stakeholders still face questions over funding, regulatory sovereignty and how common rules can operate across Africa’s different currencies and financial systems. The central challenge, therefore, is no longer whether Africa can move money digitally, but whether its countries can agree on rules that allow that money to move freely across their borders.